The Assumptions You Didn't Underwrite: Operational Diligence Before the Signature
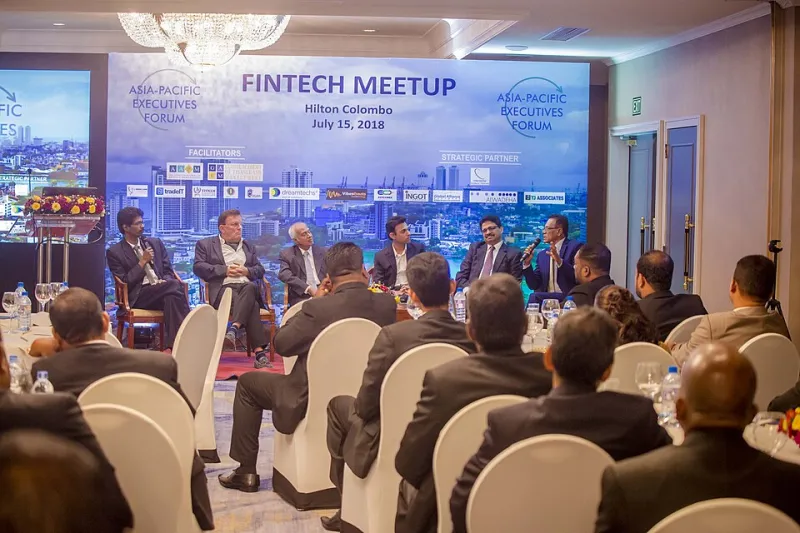
Photo: RajuRagus2018, CC BY-SA 4.0, via Wikimedia Commons
Every deal model contains a fiction, and it usually lives on a single tab. Under a heading like Operations — Normalized, capacity, service levels, and cost-to-serve are compressed into a handful of cells calibrated to a year that never quite existed. The revenue line is defended with customer data. The cost line is defended with comparables. The middle, where work actually gets done, is defended with a footnote.
That footnote is the diligence gap. It is not a failure of rigor so much as a failure of sequence: the model needs a number before the evidence arrives, so an assumption is entered, and the assumption then becomes the reference point against which every later finding is judged. By the time an integration team can test it, the deal is priced and the narrative is fixed.
Why Operations Becomes Arithmetic
Financial diligence has a mature discipline behind it. Quality of earnings work has standard procedures, standard questions, and standard skeptics. Operational diligence is younger and less standardized, which means it is often scoped by whoever is available rather than by what the thesis requires. When time is short, the operating review collapses into a series of confirmations: yes, there is a plant; yes, there is a service desk; yes, headcount reconciles to payroll within tolerance.
Confirmation is not testing. A buyer who confirms that a distribution center exists has learned less than a buyer who asks what proportion of its volume depends on two carriers, one warehouse management system, and a supervisor who has not taken a vacation in three years.
Four Assumptions That Rarely Get Tested
The service delivery baseline
Most models assume service levels hold. In practice, service levels are frequently maintained by informal effort: expedited freight, weekend shifts, spreadsheets maintained by one analyst, favors between department heads. None of that survives a change of ownership intact, and none of it appears in a service-level report. The diligence question is not what the service level is, but what it costs to produce, and which parts of that cost are discretionary.
System dependencies
The integration cost estimate is usually built from license counts and headcount. It rarely accounts for the systems that quietly do work no one has documented: the pricing engine bolted onto the ERP, the middleware that reconciles two customer masters, the reporting layer that exists because the general ledger cannot answer a basic question. Each of these becomes a workstream after close. Few of them appear in the model.
Management capacity
Synergy plans assume the existing leadership team will execute the integration while running the business. That assumption is nearly always wrong, and it is measurably wrong: the same people are already at capacity, and the integration does not arrive with a reduced operating load. Diligence should establish which roles are single points of failure, which are already stretched, and what backfill would cost.
Run costs that arrive after the synergy
Cost synergies are usually stated gross. The offsetting costs — duplicate licenses during transition, retention payments, severance, temporary labor, consulting, and the productivity dip that follows any system change — are real, recurring for a period, and seldom priced at the same level of confidence as the savings.
A Working Checklist
The following questions are not exhaustive, but they consistently surface the assumptions most likely to be wrong:
- Which customer-facing commitments are contractual, and what penalties apply if service levels slip during transition?
- Which business processes depend on a single individual, and what is the documented succession plan for each?
- Which systems hold data that no other system can reconstruct, and who owns the mapping?
- What is the current cost of expediting, overtime, and contractor labor, and how much of it is embedded in the reported run rate?
- Which vendor contracts contain change-of-control, assignment, or volume-commitment clauses that activate on close?
- What capital expenditure has been deferred, and what is the catch-up cost in the first twenty-four months?
- Which integration costs are one-time, and which persist into the steady state?
Fitting the Work to the Timetable
Operational diligence fails most often because it is scoped too broadly to finish. A better approach is to invert the sequence: start with the assumptions that carry the most value in the model, and test only those to a defensible standard. A synergy target that depends on consolidating three distribution sites deserves site-level evidence. A working capital assumption that turns on payment terms deserves a look at the actual invoice and collection cycle, not the policy document.
It also helps to separate what is being bought from what is being inherited. Assets transfer cleanly. Obligations, habits, and workarounds transfer less cleanly, and they are where integration budgets are lost.
Pricing Integration Before the Signature
The purpose of this work is not to find reasons to walk away. It is to move cost from the post-close column, where it arrives as a surprise with no negotiating leverage attached, into the pre-close column, where it can be priced, allocated, and reflected in the purchase agreement. A buyer who knows the true cost of integration negotiates a different deal than one who discovers it in month seven.
Operations will always require assumptions. The discipline is to know which ones you have made, to state them explicitly, and to test the small number that the deal cannot survive being wrong about.